

Mortgage rates finally had a better week, with Thursday bringing the biggest daily drop in 3 months and Friday adding enough improvement to claim the lowest levels in 2 weeks.
Granted, "2-week lows" won't sound especially exciting to anyone who remembers where rates were at the end of August. Most of the damage remains intact. But after weeks of improvements that barely survived long enough to make the news, this one deserves some attention.
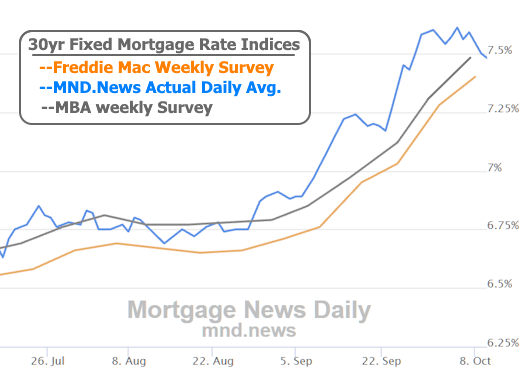
One of the more encouraging developments actually happened before Thursday's big drop. Rates jumped to new long-term highs on Wednesday morning, then almost completely recovered by the afternoon.
What's behind the improvement?
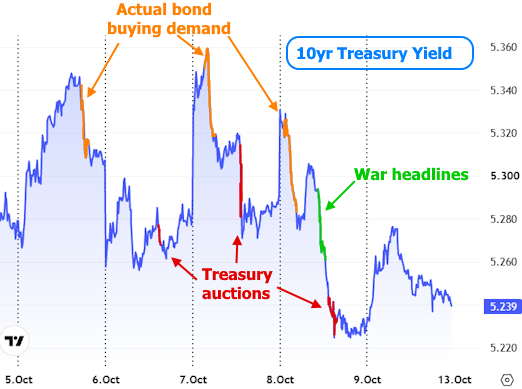
Headlines surrounding the Iran war and solid demand at Treasury auctions contributed, but there wasn't one big development that neatly explained the entire move. Some of the improvement appeared to reflect investors deciding that bond yields had risen enough to make buying more attractive.
Why do we care? Because bond buying pushes yields/rates lower, including mortgage rates. After a prolonged rate spike, when buyers finally show up, it can set the stage for a ceiling in rates. Several successive recoveries from long term highs above 5.30% in 10yr Treasuries offer some evidence that such a ceiling could be taking shape.
Of course, a ceiling is only useful if it continues to be a ceiling! There's never any way to be sure that will happen in advance. Even the impressive reversals from past examples of long-term highs required help from a meaningful change in economic data or major news developments. In other words, even though we have some evidence of investors finally stepping in to buy bonds at these levels, rates won't necessarily keep falling simply because they've finally had a good week.
Next week offers a critical opportunity. The Consumer Price Index (CPI) and Producer Price Index (PPI) will provide fresh evidence on inflation at the consumer and producer levels. Lower-than-expected readings could give the recovery a stronger foundation and ease pressure on the Fed to keep hiking. Higher readings could quickly undo the improvement and put recent highs back in play.
For now, this is the most convincing push back against the recent rate spike we've seen. Whether it becomes something worth celebrating will depend on what comes next. Fortunately, we won't have to wait long for a meaningful test.
