

At 9:44am ET on Wednesday, this week's rate story was mostly about waiting for next week's economic data. At 9:45, an unlikely report made the wait a lot more uncomfortable.
The report was S&P Global's preliminary Purchasing Managers' Indexes, or PMIs. They measure business activity in manufacturing and services, and they almost never have a major impact on rates. This time, both readings blew past expectations by the widest margins in years and reached their highest levels in years. Companies also reported input costs rising at the fastest pace in nearly 4 years, with selling prices and Employment picking up as well.
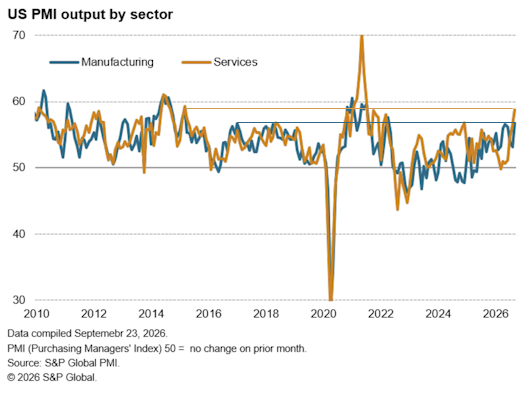
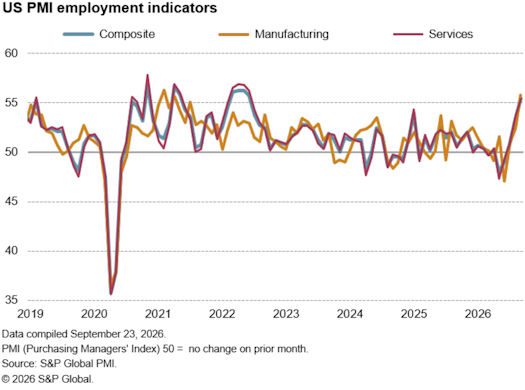
Bond traders began selling as soon as the numbers came out. The 10yr Treasury yield jumped through 5%, and the selling continued well beyond that first reaction. This was the week's only economic report with any plausible connection to next week's much more consequential ISM surveys, job openings report and monthly jobs report.
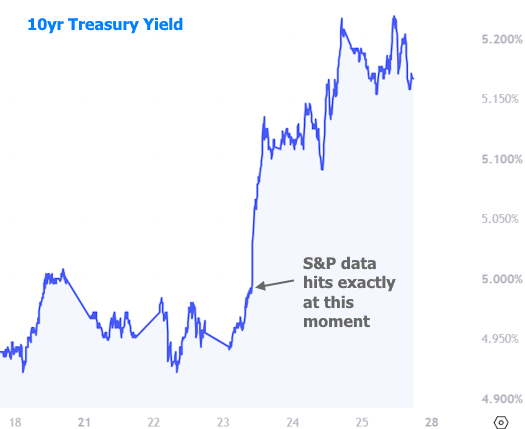
So why did the market suddenly care about a report it usually shrugs off? In short, last week's Fed meeting had traders on the edge of their seats. After Fed Chair Kevin Warsh's press conference suggested more hikes were coming, traders began worrying that the market was behind the curve in terms of pricing in the potential policy path. Since then, several Fed officials have suggested that the recently updated rate outlook could prove too low if the economy keeps strengthening or inflation turns out to be driven more by demand.
Wednesday's PMI pushed on both of those nerves at once because it raised the risk that next week's econ data (the reports that REALLY matter) could be similarly strong. It's also worth noting, that it was just the latest in a series of unpleasant surprises for the rate outlook that began in earnest at the late August Jackson Hole speech. All told, longer-term Fed Funds Rate expectations have moved up almost 0.75% since then.
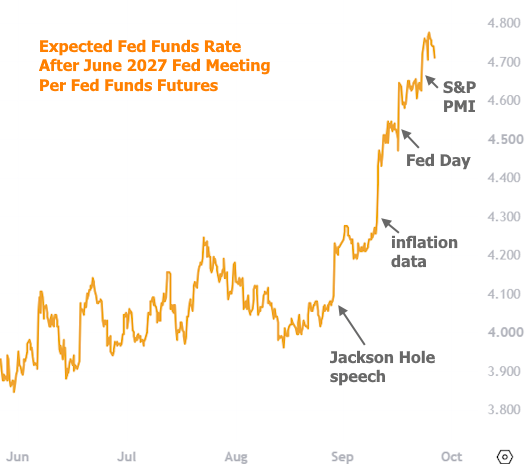
What followed was what we refer to as a repricing of the rate outlook: a sudden, widespread rethink of how many Fed hikes might be needed and how soon, marked by sharply higher bond yields and mortgage rates. It's essentially a Pandora's Box of upward pressure on rates with self-sustaining momentum that can last several days without any new justification.
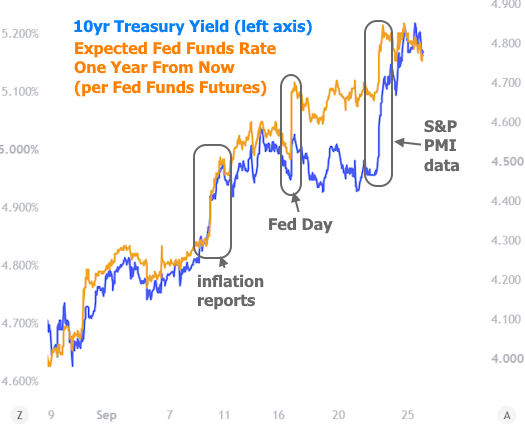
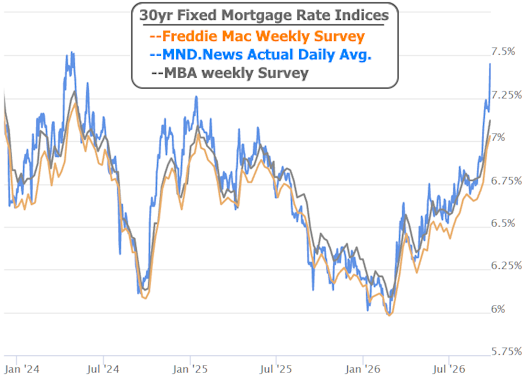
In the current case, the repricing phenomenon played out on Wednesday and Thursday. Friday brought a semblance of bond market recovery, but it required a fairly sharp drop in oil prices. Mortgage rates were initially reluctant to take the bond market's cues and they actually started the day even higher. Thankfully, by the end of the day, a series of updates from mortgage lenders (which came out much later than normal) brought the average just under Thursday's latest levels.
While that's a victory for Friday afternoon, rates still ended the week up roughly a quarter point versus last week.
Next week will help determine whether this week's scramble was a false alarm or an early warning. Oil and war headlines still matter, but the market's most pressing question is whether economic data makes the case that the Fed's latest rate forecast is already out of date.